How Business Payment Processing Works
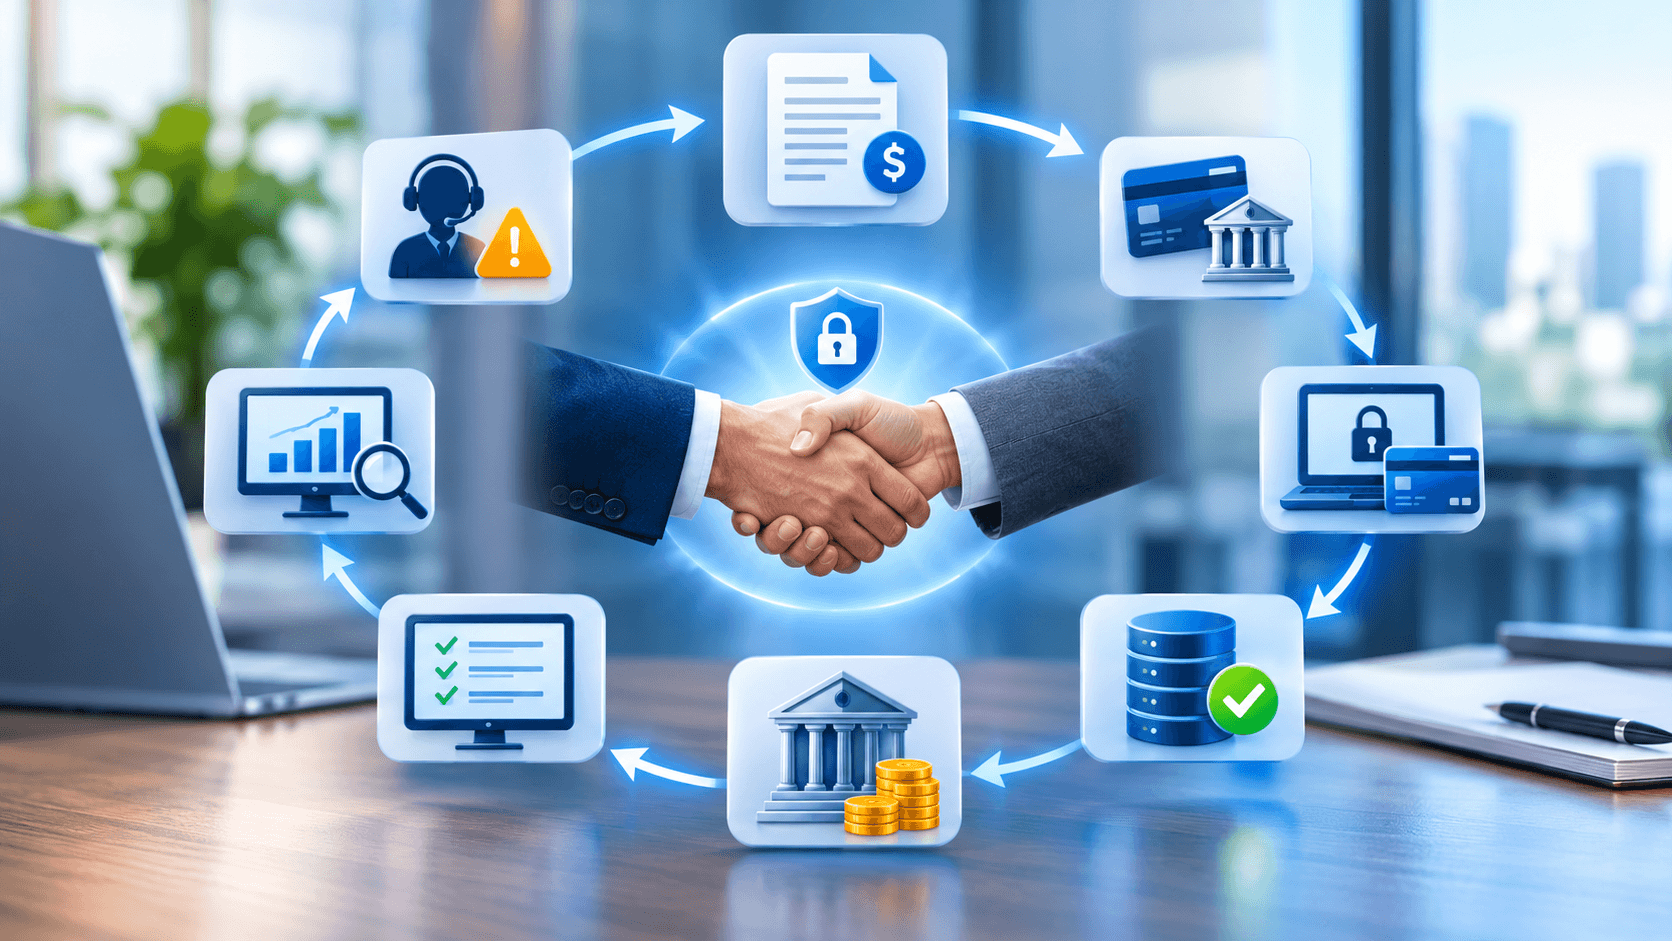
Business-to-business transactions often involve several stages before a payment is completed and recorded. A company may issue an invoice, receive a payment through an approved channel, process the transaction, receive settlement funds, and reconcile the payment with its financial records. Each stage needs to work properly for the overall process to remain efficient.
B2B payment processing refers to the activities and technology involved in accepting, handling, and completing payments between businesses. Depending on the payment method, the process may involve payment gateways, processors, banks, card networks, and business software.
Understanding the steps can help companies identify unnecessary delays, improve payment workflows, and make better decisions when choosing a payment provider.
Step One: Creating the Invoice or Payment Request
The process often begins when a business issues an invoice or requests payment for products or services. The invoice should clearly identify the parties involved, the amount due, the relevant products or services, payment terms, and the due date.
Accurate invoices help customers understand what they are paying for and reduce the possibility of disputes. Businesses should also include clear instructions explaining how payment can be completed.
Digital invoicing can make this stage more convenient. A company may send an electronic invoice with a payment link or direct customers to an online payment portal.
The payment request should be connected to the company’s accounting records so that finance teams can track outstanding balances and identify when a payment has been received.
Step Two: Selecting a Payment Method
After receiving the invoice, the customer chooses an accepted payment method. Depending on the business arrangement, this may include a commercial credit card, debit card, ACH transfer, or another supported channel.
Different methods follow different processing procedures. Card payments typically involve authorization through a payment processor and relevant card networks. ACH payments follow bank-to-bank transfer procedures and have their own authorization and processing requirements.
Businesses should provide payment options that reflect customer preferences and operational needs. They should also explain any relevant fees or payment terms clearly.
Step Three: Secure Payment Information Entry
The customer submits the required payment information through an approved channel. This may be a hosted payment page, online portal, point-of-sale device, or another secure interface.
Protecting payment information is essential. Businesses should use appropriate security technology and avoid collecting sensitive details through unsecured communication channels.
Encryption can help protect information during transmission, while tokenization can reduce the need to store actual card details in business systems. Access controls can also help ensure that only authorized users manage payment information.
Companies should understand the security responsibilities associated with their payment environment and review the safeguards offered by their provider.
Step Four: Authorization and Transaction Processing
For card payments, the processor routes the transaction through the relevant payment network and financial institutions to request authorization. The transaction may be approved or declined depending on the available information and applicable controls.
Authorization is not the same as final settlement. It indicates that the transaction has received an approval decision at that stage, but the funds may not yet have been deposited into the business’s bank account.
ACH transactions follow a different process involving bank account information, authorization, and clearing procedures. Businesses should understand the relevant timing and return possibilities.
The payment provider’s technology helps manage the transaction flow and communicates the result to the customer and merchant.
Step Five: Capture and Settlement
After a card transaction is authorized, it may need to be captured according to the payment arrangement. The transaction then moves through the settlement process, during which funds are transferred through the relevant financial institutions.
Settlement timing can vary based on the payment method, provider, banking arrangements, transaction details, and business days.
Businesses should ask providers how settlement works and when funds are expected to reach their accounts. This information can help finance teams plan cash flow and manage operating obligations.
Companies should also understand how refunds, reversals, and transaction adjustments are handled.
Step Six: Recording and Reconciliation
Once payment information becomes available, the business needs to update its financial records. Reconciliation involves matching payment transactions with invoices, customer accounts, deposits, and accounting entries.
This step is important because it helps confirm that the correct amount has been received and recorded.
Manual reconciliation can become difficult when a company handles many transactions across different systems. Integrated payment technology can help connect payment records with accounting software and ERP platforms.
Businesses should evaluate reporting tools and integration options when selecting a provider. Accurate transaction references and clear settlement reports can make reconciliation easier.
Step Seven: Monitoring Fees and Payment Performance
Payment processing involves expenses that should be reviewed regularly. These may include interchange, assessment charges, processor fees, gateway costs, equipment expenses, and other service charges.
Businesses should review statements to understand the total cost of accepting payments. They should also monitor transaction approval rates, payment failures, refunds, and chargebacks where relevant.
Paytechtrust.com offers payment cost visibility and statement analysis as part of its business payment services. Organizations reviewing their processing arrangements can consider whether detailed reporting would help them understand expenses and identify potential improvements.
Step Eight: Managing Exceptions and Disputes
Not every payment follows a straightforward path. Transactions may be declined, returned, disputed, or delayed. Customers may also request refunds or question invoice details.
Businesses should establish procedures for handling these situations. Employees need to know how to investigate payment issues, communicate with customers, and maintain accurate records.
A provider should explain the support available for transaction questions and disputes. Clear processes can reduce confusion and help businesses resolve problems more efficiently.
How Integrated Technology Supports the Process
A connected payment environment can reduce the number of manual steps involved in processing transactions. Payment information may flow between online portals, payment systems, accounting software, and ERP applications.
This can improve visibility and help employees manage invoices and payment records more consistently.
Paytechtrust.com describes payment services covering acceptance, ACH and recurring payments, integrations, reporting, and security support. Businesses can review these capabilities when evaluating how to improve their payment workflows.
Making Payment Processing More Efficient
Understanding the steps involved in B2B payment processing helps businesses identify where delays and unnecessary administrative work may occur.
From invoice creation and payment selection to authorization, settlement, reconciliation, and reporting, each stage contributes to the overall payment experience.
Companies should review their current process and determine where technology, integration, or clearer procedures could improve efficiency. A well-managed payment environment can help businesses collect funds more effectively, maintain accurate records, and support stronger financial operations.
